Oduwole says new strategy will connect verified receivables with banks, fintechs and development financiers….
The Federal Government is taking steps to use digital invoices as a financing tool for businesses, particularly small and medium-sized enterprises struggling with delayed payments and limited access to working capital.
The move followed the inauguration of the Steering Committee for the National Digital Invoicing and Financial Optimisation Strategy, NDIFS, by the Federal Government.
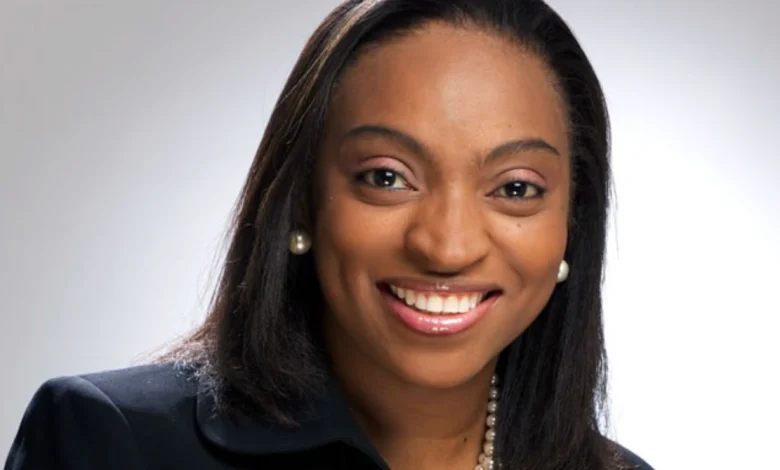
Minister of Industry, Trade and Investment, Jumoke Oduwole, said the initiative must go beyond creating a digital compliance system and instead help businesses convert verified invoices into accessible and affordable financing.
According to the minister, cash-flow constraints remain a major challenge for businesses, as funds tied up in unpaid invoices can affect production, inventory levels, supplier payments and the ability of companies to pursue new export opportunities.
She said the government’s objective is to develop what she described as a national receivables-finance corridor, allowing verified invoices generated by exporters, manufacturers, agro-processors, fast-moving consumer goods businesses and eligible public-sector counterparties to serve as a basis for obtaining working capital.
Oduwole said the proposed system would bring together four key components.
The first is a trusted digital infrastructure capable of authenticating invoices and validating transaction data. The second is a legal framework that provides certainty around the assignment and enforcement of receivables, including priority and collateral arrangements.
The third component would connect businesses to potential sources of financing, including commercial banks, development finance institutions, fintech companies, insurers and guarantors.
The fourth would involve the businesses and supply chains generating the receivables, including exporters, manufacturers, anchor buyers and suppliers.
Oduwole stressed that the success of the initiative would depend on how effectively these components work together.
She warned that technology alone would not resolve the liquidity challenges facing businesses if the underlying financing and legal frameworks remained weak.
The minister said the six-pillar architecture and phased implementation plan developed under the strategy must therefore be backed by clear responsibilities, deadlines and measurable economic outcomes.
She said the committee should assess its performance based on indicators such as the value of verified receivables entering the system, the amount of financing unlocked and the number of SMEs and productive suppliers gaining access to funding.
Other measures, she said, should include the cost and speed of financing, repayment performance, inventory cycles, production levels, supplier resilience and export performance.
The minister also outlined a number of principles for the committee, including ensuring that e-invoicing is designed with financing in mind from the beginning.
She called for systems that can communicate with one another rather than operating as isolated platforms, while also emphasising the need for strong data protection and cybersecurity safeguards.
Oduwole further urged the committee to begin with actual commercial transactions instead of allowing the strategy to remain at the policy and planning stage.
As part of that approach, she directed the secretariat and relevant institutions to develop a controlled 90-day pilot involving selected exporters, productive value chains and anchor businesses.
The pilot, she said, must have clearly defined and measurable outcomes that can be assessed before wider implementation.
She also called for the committee’s next meeting to focus on delivery, with a dashboard showing key milestones, responsible institutions, deadlines, dependencies, risks and decisions required to move the programme forward.
The minister said the committee’s mandate cuts across several areas of the economy, including revenue administration, monetary and financial infrastructure, securities regulation, industry, trade, insurance, development finance, SMEs and the organised private sector.
Its draft terms of reference include providing guidance on the strategy’s direction and sequencing, reviewing the implementation roadmap, identifying necessary policy and regulatory changes, improving coordination among institutions, managing delivery risks and supporting engagement with stakeholders.
For the government, the broader objective is to create a system where verified commercial transactions can become a more reliable gateway to finance, potentially easing the pressure on businesses whose cash remains tied up in unpaid receivables.